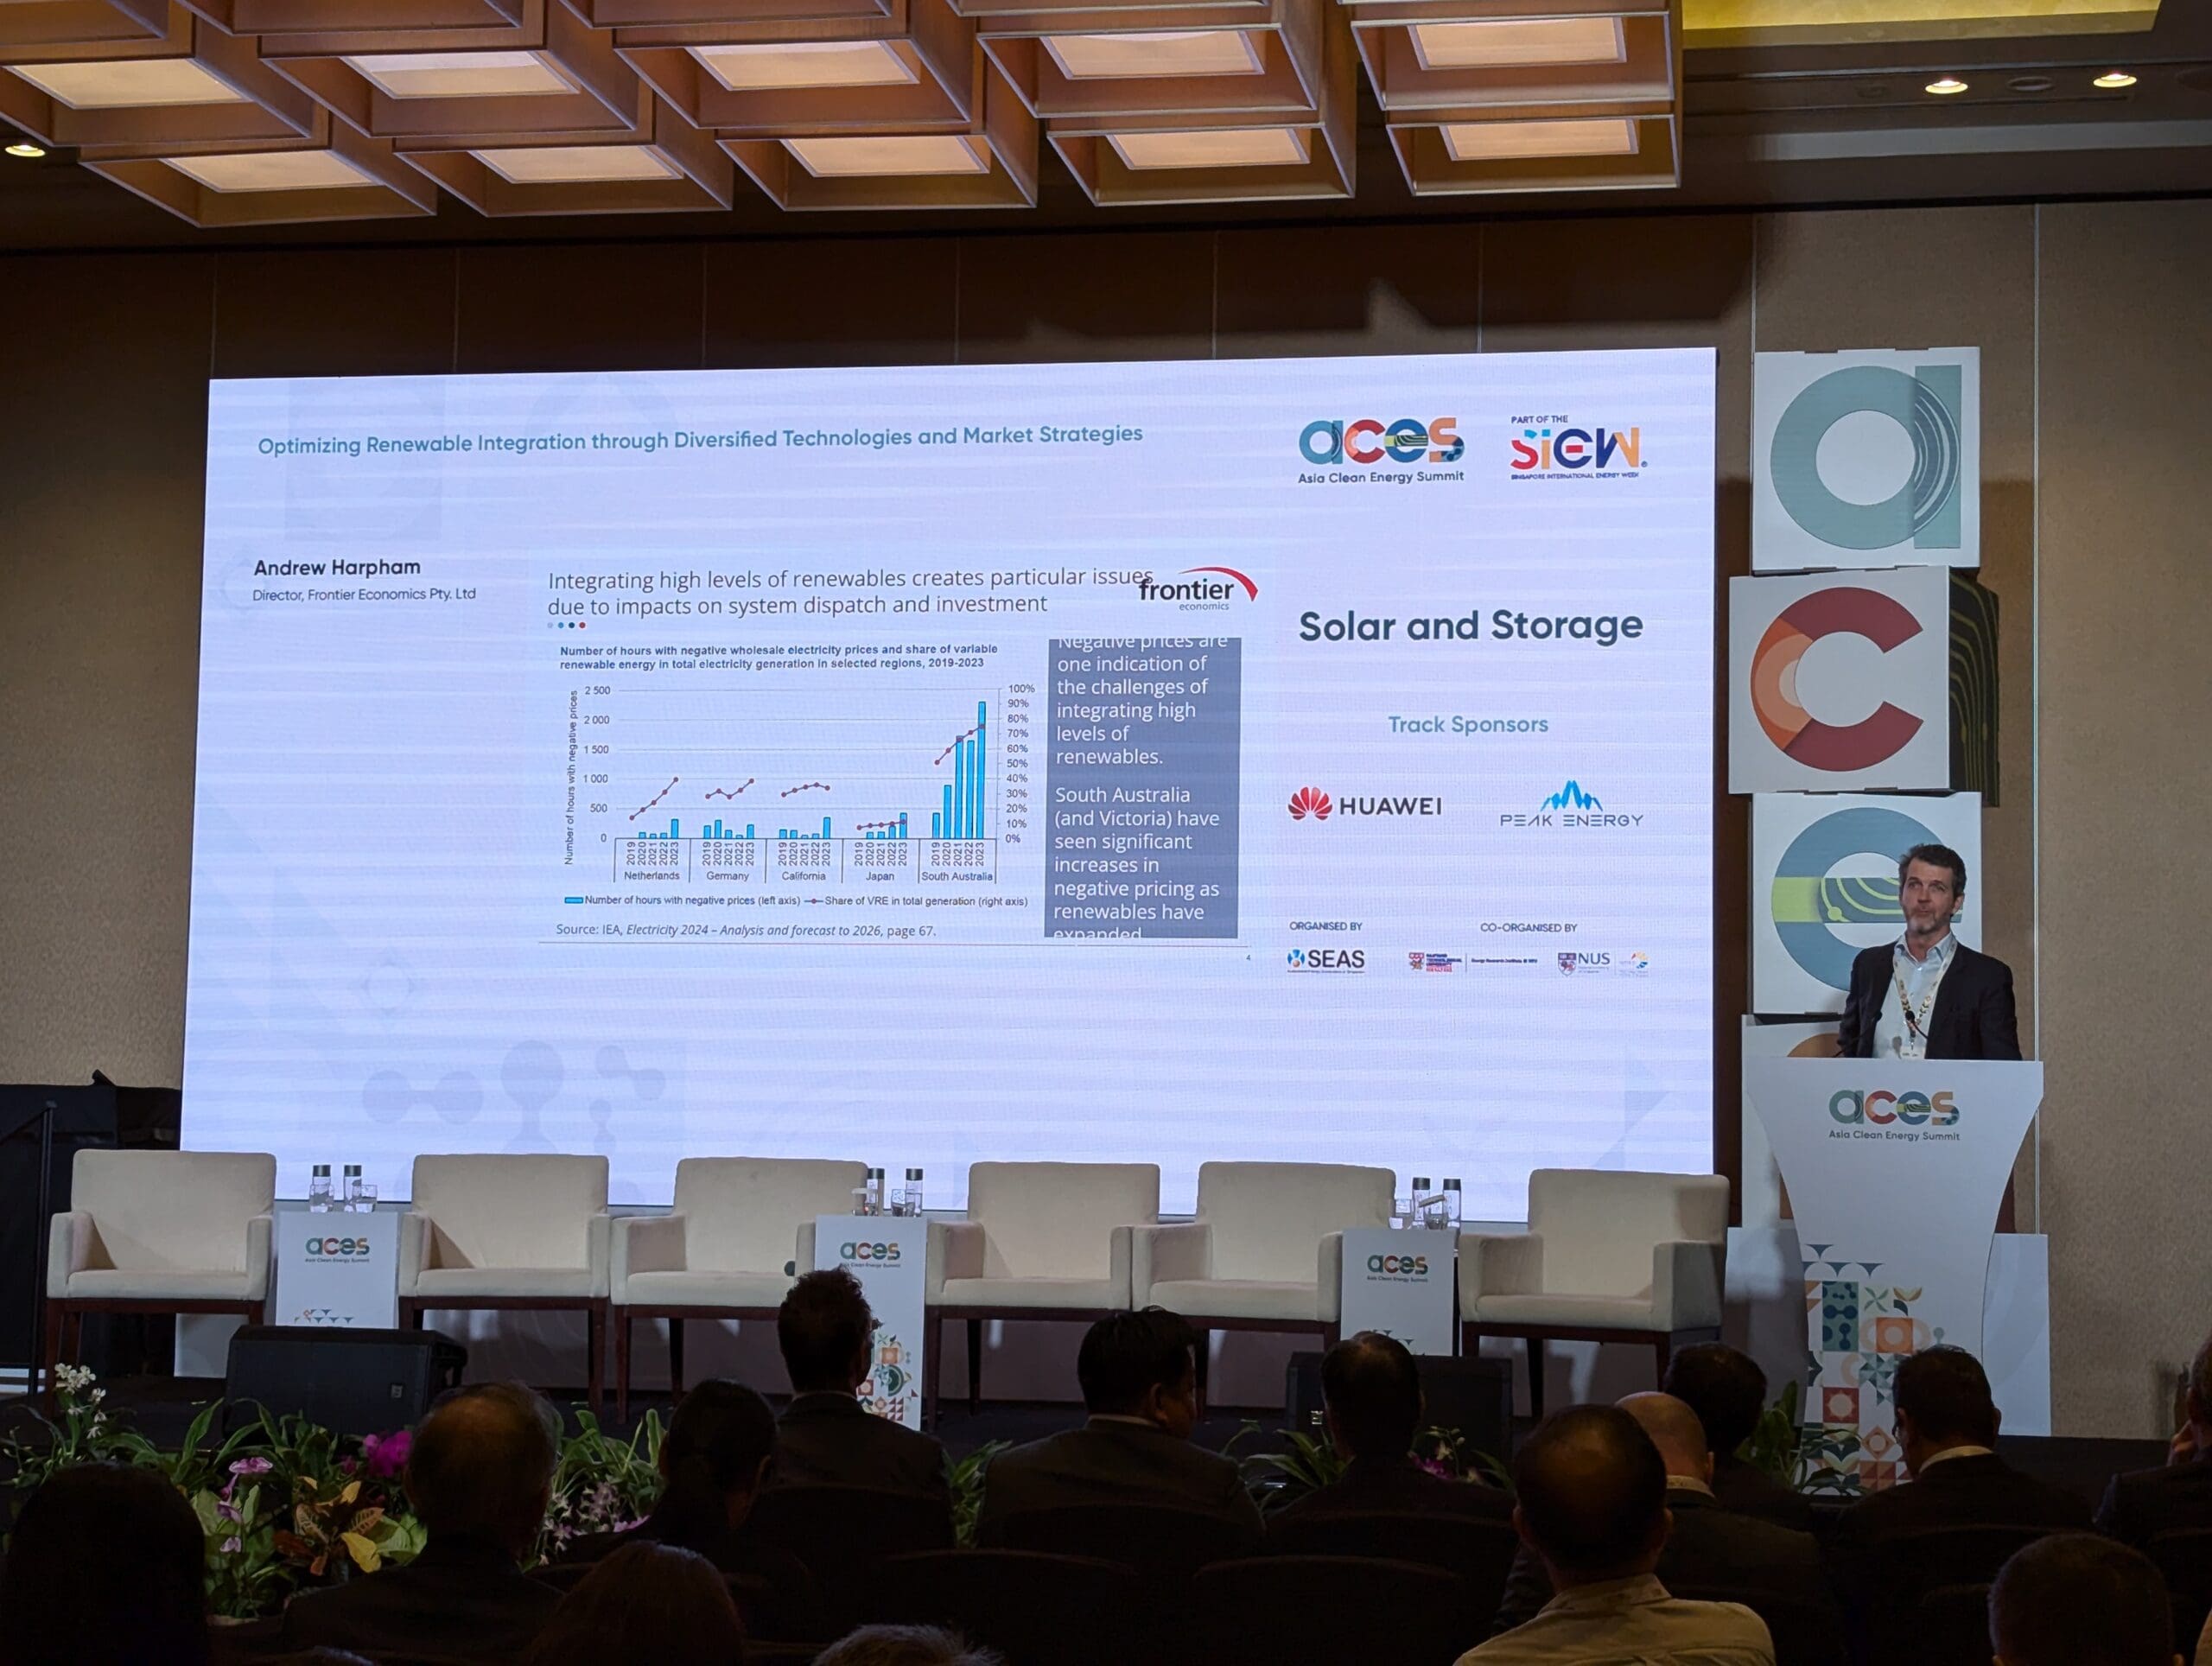
Our team recently attended Asia Clean Energy Summit at Singapore International Energy Week, and our Director Andrew Harpham presented a keynote to discuss the challenges of integrating high levels of intermittent renewable generation into the electricity grid. Below, we provide a few of his slides and commentary from his keynote.
For more information, please contact us, or reach out to Andrew and our team.
Using Whole Electricity System Cost (WESC) for the economics of generation
Andrew began by discussing the very significant reductions in renewable generation costs over time, which have meant that renewables now have the lowest Levelised Cost of Electricity (LCOE) of any generation technology.

However, the LCOE is an increasingly poor indicator of the economics of generation.
LCOE accounts for capital costs, operating costs, fuels costs (and carbon costs) of a technology.
A better guide to economic investment decisions is the Whole Electricity System Cost (WESC), which seeks to answer the question: what would be the impact of a given investment on overall system costs? WESC doesn’t just account for capital and operating costs of a given investment (which is what determines the LCOE) but also accounts for the extent to which a given investment leads to the avoidance of capital or operation costs for other generation, storage or network projects.
WESC accounts for impacts of each technology, including direct costs (as for LCOE), displaced investment, displaced generation, network impacts and balancing impacts.
Timing and response to price signals are crucial to renewable energy’s viability
When thinking about the WESC for renewable projects, it becomes clear that the timing of generation is crucial. In Australia’s electricity markets we are already seeing the market response for high levels of renewable investment: negative pricing during times of renewable generation is becoming increasingly common, with obvious impacts on the economics of renewable investment.

Pricing signals shouldn’t be masked by changing market settings, but should be responded to
These pricing signals suggest that high levels of renewable investment can be better supported with options that manage renewable intermittency. These include load shifting and storage, but also dispatchable generation.

Our energy42 modelling suggests that dispatchable generation will remain a crucial part of the generation mix, assisting to manage renewable droughts that load shifting and storage are not well equipped to manage.


Author: Andrew Harpham. Industries: Climate Change & Sustainability, Energy & Renewables. Expertise: Data Analytics, Economic Models.