Case study | 30 October 2024

Regulation and competition in telecommunications | Chorus New Zealand

What was the challenge?

The evolution of fixed line telecommunications in Australia and New Zealand can be understood through four distinct cycles:

  1. The Government Monopoly Era: The focus was on achieving universal and affordable access rather than fostering competition.
  2. Opening to Competition: In the early 1990s, there were high expectations for network competition from cable and mobile networks. However, these promises largely went unfulfilled.
  3. Access-Based Competition: From the late 1990s, this model was based on the assumption that fixed line access services would remain a monopoly. The incumbent fixed line provider supplied access services to downstream competitors, who also competed with it in retail markets.
  4. Network Separation and Regulatory Overhaul: The most recent cycle involves separating access networks from more competitive downstream functions. While implemented differently in Australia and New Zealand, the outcomes have been similar:
    • Owners of fixed access networks no longer compete in retail markets
    • Fixed broadband networks are now regulated as monopolies, similar to electricity utilities
    • Most or all services are subject to price and revenue controls
    • Costs are subject to regulatory approval

Despite the recent regulatory overhaul, there are growing doubts about whether new regulations suit the strengthening constraints from competing networks.

In recent projects for NBN Co (Australia) and Chorus (New Zealand) relating to regulatory reviews, we were asked to analyse whether competitive constraints were being understated by regulators on both sides of the Tasman. Below, we explore the economic analysis for the Chorus project.
How did we complete the economic modelling and analysis?

Analysing fixed line broadband network competition requires more than just comparing the functional abilities of fixed broadband networks to other networks. Consumers care about services and prices, not the network that services are delivered over. Competition is fundamentally about the presence of constraints on market conduct – particularly pricing.

Our work for NBN Co and Chorus noted that there were many other key features of broadband markets – including other regulations – that materially strengthen competition. We examined the following potential constraints:

  • Constraints on pricing targeted to those customers facing the most competition.
  • The usage patterns of fibre services customers and whether they could be readily targeted by suppliers of fixed wireless services (FWA) that also sell retail fibre services.
  • The existence of switching costs and barriers to expansion for key FWA competitors.
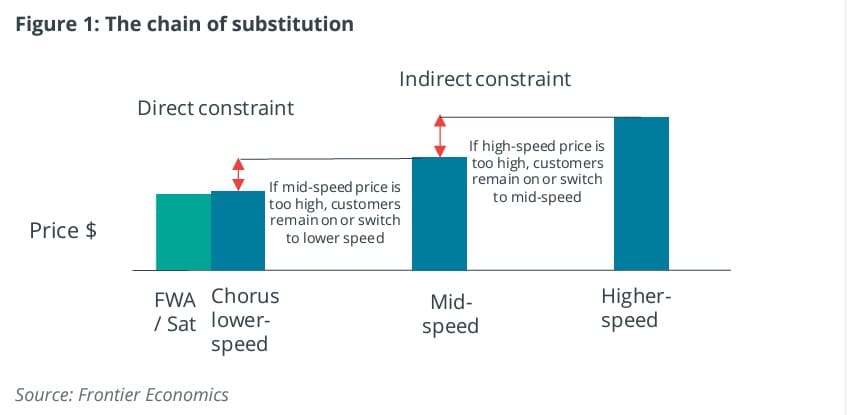
  • The likelihood of chains of substitution between areas of greater competition, such as relatively lower usage/speed services, and higher usage/speed services offered.
  • The margins for wholesale broadband services, as high margins that mean that it is very costly to lose even a relatively small percentage of customers to other networks.
  • Limited increases in willingness to pay for the superior services that the fixed broadband offers, reflected in price points for very fast services that are close to more popular products.

In analysing Chorus’ competitive environment, we applied competition analysis techniques, such as critical loss analysis, focusing on the marginal effects of hypothetical price increases. We started by examining lower-speed services and asked:

How many customers would need to switch from fixed-line to fixed wireless services (FWA) to constrain Chorus’ pricing?

What were the results?

Our analysis for Chorus revealed that the number of customers that would need to switch away from fixed networks is surprisingly small. So small that existing FWA networks could accommodate these customers without significant capacity expansion.

Having established competitive constraints for lower-speed services, we then considered whether these constraints extended to higher-speed services, where customers have fewer direct competitive options. Limiting competition would require Chorus to segment its customer base, preventing those charged higher prices from switching to lower-priced, competitively-constrained products. Our findings suggest that such customer segmentation would be challenging for Chorus to implement effectively.

Competition is the most effective regulator. In our submissions to regulatory bodies, we have shown that greater consideration should be given to both current and potential future competition. This consideration is crucial when determining the appropriate extent and types of regulation needed for fixed line broadband.

Download report

Related reading

All insights

What can we help you with?

Ask us

Get our latest insights

Sign up